When you’re a Roswell Lyft driver, a 1099 worker, getting rear-ended at a chaotic intersection like Holcomb Bridge Road and Alpharetta Highway is a special kind of nightmare. Suddenly you’re tangled in layers of insurance, liability questions, and lost income that create a legal mess. You have to understand the insurance gaps to have any hope of getting paid what you’re owed.
Key Takeaways
- Georgia law makes rideshare companies carry specific insurance, but coverage depends entirely on which “period” of activity you were in during the crash.
- Your 1099 contractor status means you’re on your own for workers’ comp and disability coverage, which most drivers don’t carry.
- If you’re in an accident, you must report it immediately to your personal insurer and Lyft, and document everything on your phone.
- Getting properly compensated often means filing claims against the at-fault driver’s insurance, Lyft’s policy, and maybe even your own uninsured/underinsured motorist coverage.
- You need to talk to a personal injury lawyer who specializes in rideshare accidents to sort through the policy limits and actually recover your medical costs and lost wages.
The Problem: The 1099 Insurance Labyrinth After a Roswell Wreck
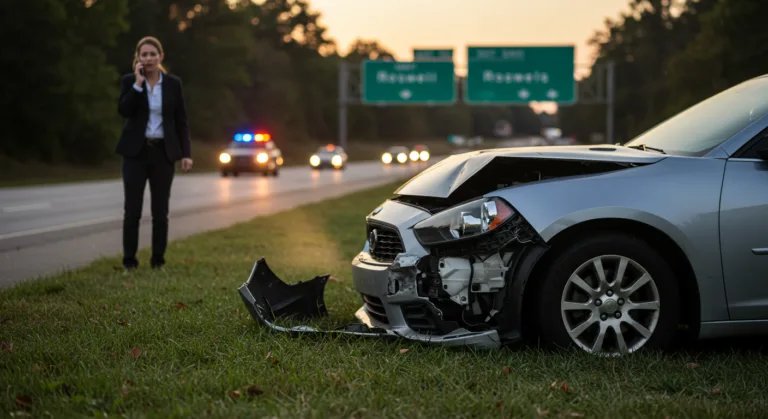
You’re a Lyft driver in Roswell, about to pick up a passenger by the Canton Street Historic District. BAM. Someone distracted by the mess on Roswell Road plows into your back bumper. Your car’s a wreck, your back is screaming, and you can’t work. As a 1099 worker, the financial dread hits almost as hard as the impact. Who’s paying for the doctor? How do you make rent when you can’t drive? This is about your entire livelihood, not just a car repair bill.
The core of the problem is your classification as an independent contractor. That means you get no traditional employee benefits, no company health plan, no paid time off, and no workers’ compensation. After an accident, the insurance picture gets complicated fast, usually involving three separate policies: the at-fault driver’s, your own personal auto insurance, and Lyft’s commercial policy. Every one of them has different conditions and limits, creating huge **insurance gaps** you can fall right into.
A lot of drivers think their personal auto insurance will cover them in a rideshare crash. This is almost never true. Most personal policies have a clear exclusion for commercial use, which means the moment you’re driving for work, that policy is worthless. This exclusion can leave you completely unprotected if you haven’t paid extra for a specific rideshare endorsement, an add-on many drivers don’t even know they need or skip because it costs more.
What Went Wrong First: Assumptions and Incomplete Information
The biggest mistake drivers make is assuming that being “on the clock” with Lyft means the company’s insurance will cover everything. That is a dangerous oversimplification. Lyft and other platforms use a tiered insurance system based on your exact “period” of activity at the moment of the crash.
For example, if you were in Period 0 (app off), it’s all on your personal auto insurance, which, as we just said, likely won’t pay. If you were in Period 1 (app on, waiting for a ride request), Lyft’s contingent liability coverage might kick in, but it usually has much lower limits than when you have a passenger. It’s only in Periods 2 and 3 (driving to pick someone up or with a passenger in the car) that the big $1 million policy is active, and even that comes with a high deductible and plenty of fine print.
Another classic error is not documenting the accident scene well enough. If you don’t have clear photos, witness contact info, and an official report from the Roswell Police Department, proving who was at fault and how bad the damage is becomes a lot harder. Drivers also sometimes put off going to the doctor, which creates a time gap that insurance companies love to use as an excuse, arguing your injuries must have come from something other than the collision.
Finally, too many drivers try to negotiate with insurance adjusters by themselves. Insurance companies are built to minimize what they pay out, and their adjusters are trained to get you to say things that can sink your own claim. Without a lawyer, you might accidentally accept a terrible settlement that doesn’t come close to covering your long-term medical care or the money you lost by being unable to work.
The Solution: A Strategic Approach to Rideshare Accident Claims
To successfully get paid what you’re owed after a rideshare accident, you need a structured plan. This is exactly where specialized legal help becomes so important. A good attorney can walk you through every step, protecting your rights and making sure you go after every dollar you’re entitled to.
Step 1: Immediate Actions at the Accident Scene
After a crash, your safety and your passenger’s safety are the only things that matter. If it’s safe to do so, follow these steps:
- Get Safe: If the car still drives, move it out of traffic. Turn on your hazard lights.
- Check on Everyone: Check yourself and any passengers for injuries. Call 911 right away if anyone is hurt.
- Call the Police: Get an officer out there, even if the crash seems minor, especially in a busy spot like the GA 400 corridor near North Point Parkway. Ask the Roswell Police Department or the Fulton County Sheriff’s Office to file a report. That report is a key piece of evidence for your claim.
- Document Everything: Your phone is your best tool. Take tons of photos and videos of the scene, the damage to both cars from different angles, skid marks, traffic signs, and any injuries you can see. Get the names and numbers of any witnesses.
- Get Their Info: Swap information with the other driver. You need their name, insurance card, driver’s license number, and license plate.
- Do NOT Admit Fault: Don’t say “I’m sorry” or anything else that sounds like you’re taking the blame. Just stick to the facts of what happened.
Step 2: Reporting the Accident and Seeking Medical Attention
Once the scene is handled, the next 24-48 hours are about protecting both your health and your claim:
- Report to Lyft: Report the accident immediately through the Lyft app or by calling their support line. Give them the facts, nothing more.
- Report to Your Insurer: You have to notify your personal auto insurance company. Be honest that you were driving for Lyft. If you have that rideshare endorsement, now is when it matters.
- See a Doctor: Even if you feel okay, get checked out by a doctor within a day or two. Injuries like whiplash can take time to show up. Go to an urgent care clinic or your regular doctor. If the injuries are bad, you may be taken to a hospital like North Fulton Hospital or Emory Johns Creek Hospital. These detailed medical records become the foundation of your injury claim.
Step 3: Understanding the Insurance Field
This is where being a 1099 worker makes everything so much more difficult. Georgia has a law, O.C.G.A. Section 33-1-31, that requires transportation network companies (TNCs) like Lyft to carry certain amounts of insurance, but the coverage that applies to you depends entirely on what “period” of activity you were in:
- Period 0 (App Off): You’re on your own. Your personal auto insurance is the only policy, and if it has a commercial-use exclusion (it probably does), you could have zero coverage.
- Period 1 (App On, Waiting for Request): Lyft’s contingent liability policy might kick in here, providing at least $50,000 per person/$100,000 per accident for bodily injury, and $25,000 for property damage. It’s a backup, not your primary coverage.
- Periods 2 & 3 (En Route to Passenger or Passenger in Car): This is when Lyft’s $1,000,000 third-party liability policy is supposed to apply, along with uninsured/underinsured motorist (UM/UIM) coverage. But you still have to deal with Lyft’s high deductible, which is often $2,500.
The big challenge for a Lyft driver in Roswell is that Lyft’s policies are designed mainly to cover third-party liability, that is, damage you cause to other people. They don’t directly pay for your lost wages or your own pain and suffering. That money has to come from the at-fault driver’s insurance or from a UM/UIM claim. Since you’re a 1099 contractor without workers’ comp, this gap can be financially devastating if the other driver has little or no insurance.
Step 4: Engaging Legal Counsel
For any serious accident, this step is not optional. You need an attorney who specializes in Georgia personal injury law and knows the ins and outs of rideshare cases. They will:
- Investigate the Accident: A good lawyer will gather the police report, track down witnesses, pull traffic camera footage from places like the Roswell Department of Transportation, and collect all your medical records.
- Determine Liability: They will clearly establish who was at fault and then identify every possible source of recovery, not just the obvious ones.
- Navigate Insurance Policies: They know how to read the fine print on the at-fault driver’s policy, your own policy, and Lyft’s policy, specifically looking for ways to use Lyft’s uninsured/underinsured motorist coverage to your advantage.
- Calculate Damages: Your lawyer will accurately calculate all of your losses, including past and future medical bills, lost income (which is complex for a 1099 driver and requires your earnings statements), pain and suffering, and the damage to your car.
- Negotiate with Insurers: They will handle all the calls and emails with the insurance adjusters, fighting to get you maximum compensation instead of a quick, lowball offer.
- File a Lawsuit: If the insurance companies refuse to be fair, your lawyer will be prepared to file a lawsuit in the proper court, which could be the Fulton County Superior Court.
Going it alone often means you risk accepting a low settlement that doesn’t cover your future needs. Worse, your claim could get denied on a technicality. For example, just arguing with an insurer about which “period” you were in can stall your claim indefinitely, but an attorney can use your rideshare app data to prove your status and shut down that argument.
The Result: Securing Complete Compensation and Peace of Mind
With a strategic approach and an experienced lawyer, a Lyft driver in Roswell can dramatically improve their odds of getting full compensation. The goal is to make you financially whole, covering the bills you have today and the ones you’ll face down the road.
For one driver, getting rear-ended on Woodstock Road near the Sweet Apple Village entrance was a disaster. The first offer from the other driver’s insurance wouldn’t have even covered his medical co-pays. As a 1099 contractor, he had no sick pay or workers’ comp. His attorney immediately took over, gathering all the medical records, getting opinions from specialists about future therapy, and carefully calculating lost income from the driver’s past Lyft earnings data. This meant proving his average daily income, factoring in the time his car was out of commission, and projecting future losses from his injuries.
The attorney first went after the at-fault driver’s policy, and after it was clear that wasn’t nearly enough, he filed a claim against the rideshare company’s own uninsured/underinsured motorist coverage. After some tough negotiations backed by the threat of a lawsuit, a settlement was finally reached that paid for all medical bills, the property damage, a large chunk of his lost income, and a fair amount for his pain and suffering. This result gave the driver the financial stability he needed to actually focus on his recovery.
This outcome is common. Yes, recovering damages when you’re a rideshare driver is complicated because of your independent contractor status and the confusing layers of insurance. But with the right legal guidance, a driver can bridge those insurance gaps and get the compensation they deserve. A lawyer will use specific Georgia laws, like O.C.G.A. Section 51-12-4 on personal injury damages, to make sure every aspect of your harm is included in the claim.
The key takeaway is that while the system is complex for 1099 rideshare drivers, it is not impossible to navigate. With a good legal team, a driver can turn a confusing and stressful wreck into a successful recovery, which is what lets you rebuild your life and get back to earning an income.
What are the Lyft driver “periods” of activity?
Lyft breaks down your status into different “periods” that determine insurance coverage: Period 0 is when the app is off. Period 1 is when the app is on and you’re waiting for a ride. Periods 2 & 3 are when you’re on the way to a passenger or they are in your car. Your coverage changes drastically between these periods.
Will my personal auto insurance cover a Lyft accident?
Almost certainly not. Standard personal policies have a “commercial exclusion,” which means they won’t cover you while you’re working. You need a specific rideshare endorsement on your policy or a separate commercial policy to be protected.
How do I prove lost wages as a 1099 worker?
Because you don’t get workers’ comp, you have to prove what you would have earned. This requires careful documentation, including your past tax returns, bank deposits, and detailed earnings statements from the Lyft platform itself to establish your average income before the crash.
What happens if the other driver has bad insurance?
If the at-fault driver is uninsured or their policy limits are too low to cover all your bills and lost wages, you may be able to file a claim using your own uninsured/underinsured motorist (UM/UIM) coverage or Lyft’s UM/UIM policy, depending on which “period” you were in.
Should I give a statement to an insurance adjuster?
No. You should always consult with an attorney before you give any detailed statement to any insurance adjuster. An adjuster’s job is to protect their company’s bottom line, and they are trained to get you to say things that can reduce the value of your claim.