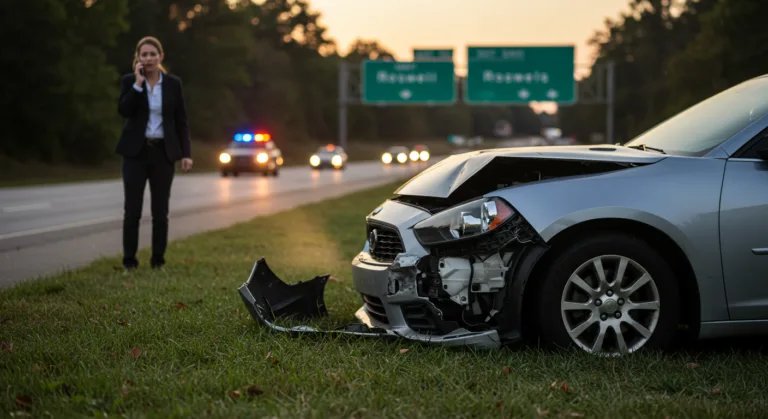
Michael, a Lyft driver out of Marietta, was working his way through the familiar stretch of Cobb Parkway near the Big Chicken, just like any other night. He’d just dropped someone off at the Marietta Square Market and was heading for his next pickup. That’s when a distracted driver, glued to her phone, blew through the intersection at Roswell Road and East Piedmont Road and rear-ended his sedan hard. This Lyft accident in Marietta wrecked Michael’s car and gave him a nasty case of whiplash, sparking immediate, panicked questions about his on-app insurance. How was he going to pay his medical bills or cover his lost income?
Key Takeaways
- When you’re on a ride or heading to one, Lyft’s insurance provides $1 million in third-party liability coverage.
- Drivers need to know the three insurance periods (offline, available, on-app) to figure out who pays after a wreck.
- Georgia law (O.C.G.A. Section 33-1-24) sets specific insurance rules for Transportation Network Companies like Lyft.
- Gathering evidence on the spot, photos, witness numbers, is absolutely essential for any rideshare accident claim.
- Talking to a lawyer who specializes in rideshare accidents can help you sort through the mess of claims against Lyft’s insurance and the other driver.
The Immediate Aftermath: Assessing the Scene and Initial Steps
The impact slammed Michael forward and then snapped his head back against the headrest. Dazed, he wrestled the car over to the shoulder. The other driver, a young woman named Sarah, was shaken up and apologetic. After making sure he wasn’t seriously injured, Michael’s first move was to call 911. Officers from the Marietta Police Department showed up fast, secured the area, and started a report. That police report is gold, because it documents the accident specifics, including Sarah’s admission that she was distracted. Michael also did the smart thing and took a ton of photos of both cars, the intersection, and the damage before anything was moved. He swapped insurance info with Sarah, making a note of her personal policy details.
What Michael didn’t realize at that moment was the tangled web of insurance policies that get involved in a rideshare accident. His own personal auto insurance, Sarah’s policy, and Lyft’s commercial coverage would all get dragged into this. This complexity surprises a lot of drivers. Most people think their personal policy has them covered, but that’s almost never the case when you’re driving for a Transportation Network Company (TNC).
Understanding Lyft’s On-App Insurance Policy in Georgia
Lyft, and every other TNC, uses a multi-tiered insurance structure that changes based on what you’re doing in the app. This system, which is required by Georgia law, is meant to fill the gaps left when your personal auto insurance policy refuses to cover commercial driving. The specific statute is O.C.G.A. Section 33-1-24, and it lays out exactly what insurance TNCs must carry. According to the Georgia Office of Commissioner of Insurance, this law guarantees a baseline of financial responsibility for every rideshare trip in the state.
You’re always in one of three coverage periods:
Were you in a car accident?
Insurance adjusters are trained to settle fast and pay less. Most car accident victims leave an average of $32,000 on the table.
- Offline: The Lyft app is off. Your personal auto insurance is all you have. Lyft provides zero coverage.
- Available (App On, Waiting for a Request): You’re logged in but waiting for a ping. In this window, Lyft provides a limited, contingent liability policy. It’s typically $50,000 per person for bodily injury ($100,000 per accident) and $25,000 for property damage. But this only applies if your own personal insurance denies the claim first.
- On-App (En Route to Pickup or During a Ride): This is the important period for Michael. Once you’ve accepted a ride and are driving to the passenger, or when the passenger is in your car, Lyft’s powerful commercial policy takes over. This policy provides $1 million in third-party liability coverage for bodily injury and property damage. It also has uninsured/underinsured motorist coverage and contingent complete and collision, but that comes with a high deductible, often around $2,500.
Michael was on his way to pick up a passenger when he got hit, putting him squarely in that “on-app” period. So, Lyft’s $1 million policy should have applied. Getting that coverage, however, can be tricky, especially when another driver is clearly at fault.
Working through the Claims Process: A Tangled Web
After getting checked out for his neck pain at Wellstar Kennestone Hospital, Michael reported the wreck to Lyft. They pointed him toward their insurance carrier (at the time, usually a big name like Progressive or Zurich). He also called his own auto insurance company, and that’s when things started getting complicated.
Sarah’s insurance company quickly accepted liability. The problem was, her policy limits were just $25,000 for bodily injury and $50,000 per accident. Michael’s medical bills, car repairs, and lost income were already soaring past those numbers. This happens all the time. The at-fault driver’s personal policy is rarely enough to cover the damage. The National Highway Traffic Safety Administration (NHTSA) data shows that distracted driving causes serious accidents with injuries that easily exceed state minimum coverage.
Michael’s personal auto insurer, once they heard he was driving for Lyft, pointed to the commercial use exclusion in his policy. This is a standard clause. They denied coverage for his lost wages and medical bills, saying that Lyft’s commercial policy was the one that should pay.
So Michael was stuck between a rock and a hard place: Sarah’s insurance was too low, and his own policy wouldn’t touch it. He was forced to go after Lyft’s commercial policy directly. That meant he had to diligently document every single medical treatment, every physical therapy appointment at a clinic near Marietta Square, and every day of missed work. Keeping detailed records is everything. Without them, insurers have an easy excuse to delay or deny your claim.
The Role of a Legal Professional in Rideshare Accidents
Frustrated with the runaround from the insurance companies and watching the bills pile up, Michael hired a lawyer. This was a big deal. An attorney who specializes in personal injury and rideshare cases knows the TNC insurance playbook and understands the specifics of Georgia law. They know how to talk to Lyft’s adjusters and how to fight back when a personal auto carrier issues a denial.
A good lawyer would immediately start digging into several key areas:
- Lyft’s Coverage Activation: Proving Michael was “on-app” at the exact moment of the crash by getting Lyft’s trip logs and internal data.
- Policy Stacking and Subrogation: Figuring out how Sarah’s small policy interacts with Lyft’s $1 million coverage. Lyft’s policy often steps in to cover everything above and beyond the at-fault driver’s limits.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: Even though Sarah had insurance, her low limits meant she was “underinsured.” Lyft’s commercial policy includes UM/UIM coverage, which provides another source of recovery for Michael’s injuries and lost income.
- Medical Liens and Negotiations: Taking over the management of medical bills and negotiating with hospitals and clinics to lower the amounts owed, which makes sure Michael actually keeps more of the settlement money.
The attorney also helped Michael calculate the true value of his claim, factoring in not just his current bills but also future medical needs, pain and suffering, and the diminished value of his car. They put together a complete demand package for Lyft’s insurer, laying out all the damages with supporting documents.
Resolution and Lessons Learned
After a few months of negotiation, Michael’s attorney secured a settlement that covered his medical bills, lost income, and provided compensation for his pain and suffering. The money mostly came from Lyft’s commercial insurance policy, which acted as a secondary layer after Sarah’s insufficient personal policy was exhausted. The outcome made one thing perfectly clear: rideshare accident claims are much more complicated than standard Atlanta car accident claims because of all the different insurance policies involved.
For any Lyft driver in Marietta or anywhere else in Georgia, knowing those distinct insurance periods is non-negotiable. Documenting everything at the scene, from photos to witness contacts, provides the evidence you’ll need. On top of that, getting legal guidance from an attorney who knows TNC claims can be the difference between getting a fair settlement and getting your claim denied.
If you’re a rideshare driver in Georgia and you’ve been in an accident, understanding the specific insurance policies in play is the key to protecting your rights and getting fair compensation. It’s also worth looking into how things like Atlanta rideshare AI and insurance shifts are changing the claims process.
What’s the difference between “on-app” and “offline” for Lyft’s insurance?
When you’re “offline,” the app is off and only your personal auto insurance applies. “On-app” means you’re logged in waiting for a ride, on your way to a pickup, or have a passenger in the car. Lyft provides different levels of commercial insurance during these “on-app” times, with the best coverage, up to $1 million in liability, active when you’re en route to a pickup or on an active ride.
Will my personal auto insurance cover me while I’m driving for Lyft?
Almost certainly not. Most personal auto policies have a “commercial use exclusion,” which lets them deny any claim that happens while you’re working for a company like Lyft. You need to check your specific policy, but as a rule, you can’t depend on personal insurance to cover rideshare incidents.
What should a Lyft driver do right after a wreck in Marietta?
First, check on everyone and call 911 if there are injuries or bad damage. Get insurance and contact info from everyone involved. Take tons of photos of the scene, the car damage, and any injuries you can see. Report the accident to Lyft through the app right away, and also call your personal insurance company (even though they’ll probably deny it). Get medical attention immediately, even if you feel fine.
How does Georgia law handle rideshare insurance?
Georgia law, under O.C.G.A. Section 33-1-24, forces Transportation Network Companies (TNCs) like Lyft to carry specific levels of insurance for their drivers. This law makes sure there’s adequate liability coverage when drivers are working, since personal policies won’t cover commercial driving.
Can I claim lost wages if a Lyft accident puts me out of work?
Yes. If you’re hurt in a Lyft accident and can’t work, you can claim lost wages as part of your damages. This claim is usually paid from the at-fault driver’s bodily injury coverage or from Lyft’s commercial policy if it applies. Having detailed proof of your income before the accident is key to making this claim stick.