There’s a lot of bad information out there about rideshare accident claims, and it’s a huge problem for people driving for services like Lyft. Too many Lyft driver Seattle residents are out on the road with no real clue about their rights or what they’re supposed to do after a crash, especially when facing a third-party claim. The insurance policies for rideshare are so confusing that drivers are left exposed if they don’t know how it all actually works.
Key Takeaways
- Lyft’s big insurance money only kicks in once you’ve accepted a ride, not when you’re just available or driving for yourself.
- Washington State has its own laws on minimum insurance for rideshare drivers, and that affects which policy pays first.
- If you’re in an accident, you have to tell Lyft right away and get checked out by a doctor, no matter how small it seems.
- Your personal car insurance almost certainly won’t cover you while you’re working, which means you really need to think about getting a separate rideshare policy.
- A third-party claim after a rideshare wreck means you’re juggling personal insurance, commercial policies, and state laws all at once.
Myth 1: My personal auto insurance will cover me fully if I’m involved in an accident while driving for Lyft.
This is probably the most dangerous myth a rideshare driver can believe. Almost every personal auto insurance policy has a “commercial use” exclusion. That’s not fine print. It’s a core rule of the contract that says they won’t pay a cent if you were using your car for business when the accident happened. If you’re logged into the Lyft app, you’re working, and your personal policy is likely off the hook, even if you haven’t accepted a ride yet.
Just imagine you’re on I-5 near the West Seattle Bridge, app on, waiting for a ping. Someone rear-ends you. Your personal insurance company will probably deny your claim flat out, leaving you to pay for your own car repairs and medical costs. The Washington State Office of the Insurance Commissioner is clear on this: personal policies are for private driving, not for running a taxi service. This “rideshare gap” is a brutal financial shock that many drivers only learn about after they’ve already crashed.
Myth 2: Lyft’s insurance covers me from the moment I log into the app until I log out.
Lyft does have insurance, but how and when it covers you is tricky. It all depends on what “period” you’re in at the time of the crash.
- Period 1 (App On, Waiting for Request): When your app is on but you’re just waiting for a ride request, Lyft’s coverage is pretty thin. Think lower limits: $50,000 in bodily injury per person, $100,000 in bodily injury per accident, and just $25,000 in property damage. This coverage is supposed to kick in after your personal policy, but as we just saw, your personal policy probably won’t pay a dime for this period anyway.
- Period 2 (Accepted Request, En Route to Passenger, During Ride): The big guns come out once you’ve accepted a request and are on your way to the passenger or have them in the car. This is when Lyft’s $1,000,000 third-party liability policy is active, which is designed to cover bodily injury and property damage you cause to others when you’re at fault. The policy also has uninsured/underinsured motorist coverage and collision coverage, though you’ll have to pay a hefty deductible for that last one.
If you don’t get these phases straight, you can be badly exposed financially. A driver who gets hit while waiting for a request near Pike Place Market is going to discover they have far less protection than they assumed. This isn’t just a Seattle problem. A report from the National Association of Insurance Commissioners (NAIC) points out these coverage gaps are a constant headache for rideshare drivers across the country.
Myth 3: If another driver is at fault, their insurance will always pay for everything without issue.
In theory, the at-fault driver’s insurance pays for everything. In practice, it’s never that simple with rideshare. The minute a Lyft driver Seattle is in a wreck, the commercial policies make everything a mess. The other driver’s insurance company will look for any excuse to pay less, arguing that since you were working, Lyft’s commercial policy should pay first, or they might just dispute your injuries entirely.
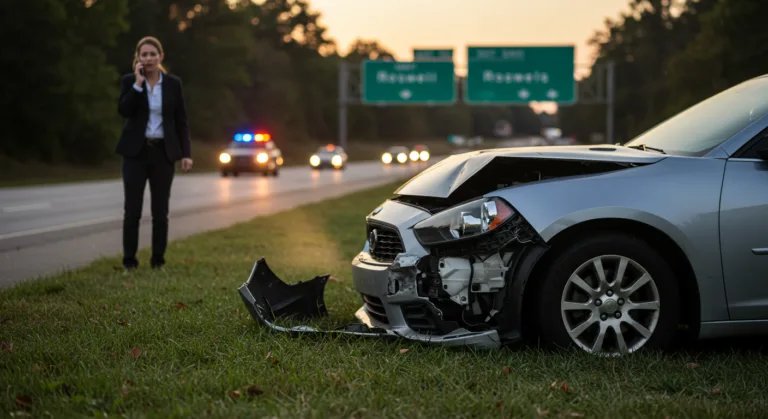
So you’re driving a passenger through Capitol Hill, and a car blows the red at Broadway and E Pike, T-boning you. It’s 100% their fault. So what? Their insurance company will still drag the process out for months and try to get you to accept a pathetic settlement offer. They’ll start digging around, questioning if you have the right insurance and trying to push liability onto Lyft’s policy. This is what a messy third-party claim looks like in real life. Getting fully paid for your medical bills, lost income, and car repairs isn’t automatic. It all comes down to a battle between these insurance policies, and it’s a fight you’ll probably need legal help to win.
Myth 4: I don’t need to tell Lyft about an accident if it wasn’t my fault or if it was minor.
Wrong. You must report *every* accident to Lyft immediately, no matter who was at fault or if it just seems like a scratch. It’s in their terms of service. If you don’t, you could lose any chance of using their insurance coverage, even if you were on an active trip. Waiting to report just makes insurance adjusters suspicious and gives them a reason to complicate your claim.
Besides, that little fender bender in Bellevue might feel fine now, but what about tomorrow? Whiplash and back injuries can take hours or even days to show up. If you haven’t reported the accident to Lyft and sought medical attention right away, it becomes an enormous uphill battle to prove your injuries are connected to the incident. So, document everything. Take photos of the scene, get witness contact info, and make sure you get a police report. A police report is gold, even if no one gets a ticket. The Washington State Department of Licensing (DOL) itself recommends reporting any accident with injuries or significant property damage, so you need that paper trail.
Myth 5: Rideshare insurance is an unnecessary expense if Lyft already provides coverage.
This thinking completely ignores that “rideshare gap” we talked about. Your personal policy won’t cover you, and Lyft’s ‘Period 1’ coverage is weak. That leaves a huge window of time where you have very little insurance, or none at all. A dedicated rideshare insurance policy, which is usually just an endorsement (an add-on) to your personal auto policy, is made specifically to cover that gap.
You can get these rideshare endorsements from a bunch of insurance providers in Washington State. They simply extend your personal coverage to that ‘Period 1’ time when you’re logged in and waiting, so you’re never unprotected. Without it, a simple accident while waiting for a fare near Lumen Field could cost you thousands of dollars out of your own pocket for vehicle repairs and medical treatment. From my experience, drivers who pay a little extra for this supplemental coverage fare much better after a crash because they don’t have to fight a denied claim from their personal insurer. It’s a small price for real peace of mind.
Myth 6: Dealing with a third-party claim after a rideshare accident is just like any other car accident claim.
A rideshare accident claim is way more complicated than a standard one. You’re not just dealing with two personal insurance companies. You’ve got your personal insurer, Lyft’s commercial insurer, and the at-fault driver’s insurer all in the mix. And trust me, every one of those companies is going to do whatever it can to pay out as little as possible, which usually means trying to shift responsibility to one of the other policies.
For example, if you’re injured in an accident as a Lyft driver, and the other driver is at fault, their insurance company will point fingers, arguing your injuries should be covered by Lyft’s commercial policy. But your personal insurer will just deny the claim because of the commercial use exclusion. You’re stuck in the middle of a bureaucratic nightmare that can be incredibly frustrating and time-consuming. To get through it, you have to understand the hierarchy of coverage and what Washington State law says, like the specific rules for transportation network companies in Revised Code of Washington (RCW) 48.177.010. It’s a three-way legal and insurance fight that’s almost impossible to win on your own.
Dealing with the fallout from a rideshare accident, especially a messy third-party claim, means you have to know how this specific insurance game is played. For a Lyft driver Seattle, getting the right rideshare insurance and knowing exactly what to do after a crash is the only way to protect your financial future. This is particularly true when you consider the potential critical steps for claims and realize how differently states handle these complex situations.
What is a “third-party claim” in the context of a rideshare accident?
It’s when you file a claim against the at-fault driver’s insurance company to get them to pay for your damages. For rideshare drivers, this gets tangled up fast because of the interplay between your personal policy, Lyft’s policy, and the other driver’s policy.
Does Washington State require specific insurance for rideshare drivers?
Yes. Washington’s law, specifically RCW 48.177, sets out minimum insurance requirements for companies like Lyft and their drivers. The rules are different for different phases of driving, so drivers should know what the law demands of them.
What should a Lyft driver do immediately after an accident in Seattle?
First, make sure everyone is safe and call 911 for emergencies. Then, exchange info with the other driver, take a ton of photos of the scene and the damage, and report the crash to Lyft through the app. Most importantly, seek medical attention right away, even for what feels like a minor symptom.
Can I lose my driving privileges with Lyft after an accident?
Lyft can deactivate your account after an accident. It usually depends on the severity, who was at fault, and your overall accident history. Reporting the incident promptly and cooperating with their investigation is always your best course of action.
How long do I have to file a claim after a rideshare accident in Washington State?
In Washington, the statute of limitations for filing a personal injury lawsuit is generally three years from the date of the accident. You should never wait that long, though. It’s always best to start the claims process as soon as possible while evidence is fresh and memories are clear.