If you get hit by a Grubhub driver in Phoenix, getting a fair settlement is a real fight. The entire system is confusing on purpose. Delivery drivers work under a tangled insurance scheme that almost guarantees a dispute over who’s liable and who pays for your injuries, which directly impacts your recovery. To get the most money from your Phoenix settlement, you have to understand their legal games and have a battle-tested plan for collecting evidence and negotiating.
Key Takeaways
- Get all your paperwork, police reports, every medical record, and photos from the scene, in your hands within 48 hours.
- You must tell your own insurance company, the Grubhub driver’s personal insurer, AND their commercial carrier about the crash right away.
- Talk to a personal injury lawyer who handles rideshare and delivery cases within the first week. You need to know your rights before you lose them.
- Keep a running tally of every dollar you’ve lost: missed paychecks, medical bills, and damage to your car. This is the foundation for your economic damages claim.
- Steel yourself for a long fight. These delivery accident settlements involve multiple insurance policies and can easily take 12 to 24 months to finally resolve.
The Initial Chaos: What Went Wrong First
I see the same mistakes over and over right after a collision with a Grubhub driver. People are in shock or just don’t get how different these accidents are. The biggest blunder isn’t getting enough evidence at the scene. You can’t assume the police report will have everything you need. I’ve found they are often incomplete, missing key details like the driver’s employment status or which insurance policy was active. I’ve seen strong cases fall apart months down the line because there wasn’t a single photo of the Grubhub delivery bag on the passenger seat or a clear shot of the road conditions.
Another classic error is talking too much to insurance adjusters before you have a lawyer. It doesn’t matter if it’s the driver’s personal policy or Grubhub’s commercial carrier, the adjuster’s job is to pay you as little as possible. They’re trained to ask tricky, seemingly friendly questions to get you to say something they can use against you. For example, just saying “I’m so sorry this happened,” which is just a polite thing to say, can get twisted into an admission that you were at fault. I tell my clients to give only the bare-bones facts and let their attorney handle any detailed conversations.
On top of that, so many people wait too long to see a doctor. The adrenaline from the crash masks the pain, but then a few days or weeks later, they’re in agony. That delay creates a “gap in treatment” that insurance companies love to exploit, arguing your injuries must have come from something else. Here in Arizona, getting checked out right away is absolutely essential. Even if you feel okay, getting an evaluation at a place like St. Joseph’s Hospital and Medical Center or Banner University Medical Center Phoenix creates a clear, dated record connecting your injuries to the crash.
Understanding the Complex Insurance Field of Delivery Accidents
The central problem with these Grubhub accident cases is the convoluted insurance setup. Grubhub and other delivery companies use a tiered insurance system that’s supposed to back up the driver’s personal policy, but it’s never that simple. In practice, Grubhub’s corporate policy only comes into play if the driver is on an active delivery, meaning they’ve accepted an order and are driving to the restaurant or to the customer. If the driver is just logged into the app waiting for an order, or is driving between hotspots, their personal car insurance is supposed to be the one on the hook.
The Arizona Department of Insurance requires these delivery companies to carry specific liability coverage for their drivers depending on what they’re doing. The liability limits are usually lower when a driver is just logged in waiting for a ping, but they’re supposed to be much higher when they’re actively transporting food. For instance, Grubhub’s policy might cover up to $1,000,000 in liability during an active delivery, but that coverage disappears if the driver hasn’t accepted an order yet. That one detail, was the app on and was an order active?, is everything.
The big problem for you, the victim, is figuring out which policy was supposed to be active when you got hit. The drivers are independent contractors and often have no idea how their own insurance works with Grubhub’s policy. This confusion predictably leads to adjusters from both insurance companies pointing fingers and denying the claim, leaving you stuck in the middle. We constantly see personal insurers say, “They were working for Grubhub, it’s not our problem,” while Grubhub’s carrier says, “They weren’t on an active delivery, so it’s not our problem.” This is exactly why you need an evidence-heavy strategy to prove who is responsible.
The Solution: A Strategic Path to Maximizing Your Phoenix Settlement
Getting the best possible settlement from a Grubhub accident in Phoenix means you need a solid strategy based on fast documentation, expert legal help, and a willingness to fight during negotiations. I’ve seen over and over that the cases with the best outcomes are the ones where the client was decisive from the very beginning.
Were you in a car accident?
Insurance adjusters are trained to settle fast and pay less. Most car accident victims leave an average of $32,000 on the table.
Step 1: Immediate Action and Complete Documentation
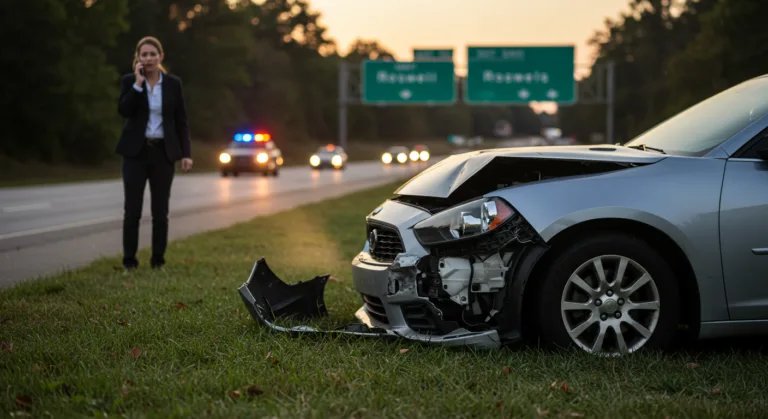
What you do in the moments right after the crash matters. A lot. First, get to safety. If you can, move your car out of traffic. Then call 911 to report the crash, especially if anyone is hurt or the cars are seriously damaged. A police report from the Phoenix Police Department (or the Arizona Department of Public Safety if you’re on a state highway like I-10 or I-17) creates an official record of what happened. Make sure the officer gets the Grubhub driver’s name, insurance info, and notes that they were working for Grubhub.
Then, turn your smartphone into an evidence-gathering tool. Take pictures and videos of:
- All the cars involved, getting shots of the damage from every angle.
- The license plates.
- The whole accident scene, including skid marks, traffic signals, and the general road conditions.
- Any injuries you or your passengers have.
- The Grubhub driver’s car, specifically looking for things like delivery bags or phone mounts that prove they were working.
- The driver’s insurance card and license.
If there are any witnesses, get their names and phone numbers. Their story could be the one thing that proves your case.
Go get medical care right away, even if you just feel a little sore. Go to an urgent care clinic, your family doctor, or an ER in Phoenix, like at HonorHealth John C. Lincoln Medical Center. This starts a paper trail for your injuries. Then, do exactly what the doctors tell you and go to every single follow-up appointment. Insurance companies will use any gaps in your treatment to argue that your injuries aren’t that bad or that something else caused them.
Step 2: Engaging an Experienced Personal Injury Attorney
This is the single most important thing you can do. You should call a Phoenix personal injury lawyer who specializes in these gig-worker accidents within a few days of the crash. A good attorney knows the specific Arizona laws, like the state’s comparative fault rule in Arizona Revised Statutes Section 12-2505, which can lower your payout if you’re found even slightly at fault. Your attorney will:
- Dig for the facts: They’ll get the police report, track down and interview witnesses, and collect all the evidence to prove the other driver was at fault. This almost always means sending a legal demand to Grubhub for data proving the driver’s app status when the crash occurred.
- Handle the insurance maze: Your lawyer will figure out all the policies that could apply, the driver’s personal insurance, Grubhub’s commercial policy, and even your own uninsured/underinsured motorist coverage, and will take over all communication. This keeps you from accidentally saying something that an adjuster can use to deny or reduce your claim.
- Calculate your true damages: An attorney will look beyond the obvious medical bills and car repairs to put a number on your pain and suffering, emotional trauma, and lost quality of life. They’ll also calculate your lost income, future medical costs, and any damage to your long-term earning ability.
- Negotiate from a position of strength: Insurance companies get serious when they know they’re up against a lawyer who isn’t afraid to go to court. Your attorney will fight for you, pushing for the maximum compensation you deserve.
If you try to do this alone, you’re almost guaranteed to accept a settlement that is far less than what your case is actually worth. Adjusters know when they’re dealing with someone who doesn’t have a lawyer, and they will use that power imbalance against you.
Step 3: Complete Documentation of All Losses
You need to become a bookkeeper for your own case. Keep a detailed file of every single expense and loss you suffer because of this accident. This file should have:
- Medical Bills: Every single invoice, receipt, and statement of benefits from doctors, physical therapists, pharmacies, and hospitals.
- Lost Wages: Get a letter from your boss that spells out the exact days you missed from work and how much income you lost. If you’re self-employed, you’ll need financial records to prove your lost earnings.
- Property Damage: Keep every repair estimate, the bill for your rental car, and receipts for any personal items that were destroyed in the crash.
- Out-of-Pocket Expenses: Track things like the mileage for driving to your doctor’s appointments, parking fees at the hospital, or the cost of hiring help because you’re injured.
This detailed financial paperwork is the foundation of your demand for economic damages. The more organized your records are, the less room an insurance company has to argue with the numbers.
Step 4: Strategic Negotiation and Litigation Readiness
Be ready to wait. The negotiation phase takes time. Your lawyer will start by sending a formal demand letter to the insurance companies that lays out the facts, details your injuries, and states the total compensation you’re demanding. That first demand is almost always answered with a lowball offer. This is normal. This is where your lawyer’s experience really pays off, as they’ll go back and forth, using the evidence we’ve gathered to push the settlement number up.
Sometimes, the insurance company just won’t offer a fair number. When that happens, we have to file a lawsuit in the Maricopa County Superior Court. Filing suit doesn’t mean you’re headed for a dramatic trial. Most of these cases still settle before ever seeing a courtroom, often in a formal process like mediation. But showing the insurance company you’re fully prepared to go to trial is what makes them take your claim seriously and strengthens your negotiating power. We prepare every single case as if it’s going to trial, because that’s what produces the best out-of-court settlements.
Measurable Results: What a Successful Settlement Looks Like
So what does a good settlement actually look like? It means you get paid back for everything you lost, both the money out of your pocket and the non-financial harm that’s harder to put a price on. It should include:
- Medical Expenses: Full payment for all of your medical care connected to the accident, past, present, and future. This includes hospital bills, surgery costs, physical therapy, prescription drugs, and counseling.
- Lost Income: You should be reimbursed for the paychecks you missed while recovering. If your injuries affect your ability to work in the future, you should also be compensated for that loss of earning capacity.
- Property Damage: Money to either fix your car or pay you the fair market value if it was totaled, along with the cost of a rental car.
- Pain and Suffering: This is compensation for the physical pain, the mental anguish, and the fact that you can’t enjoy your life the way you used to. This is often the biggest part of a settlement and depends entirely on how bad your injuries are and how much they’ve impacted your day-to-day life.
- Other Out-of-Pocket Expenses: Reimbursement for any other costs you had to pay because of the crash.
Every case is different, but a claim that’s handled correctly, with solid evidence and a good lawyer, should end with a settlement that fully covers all of these areas. We’ve had clients get settlements that not only paid off their immediate debts but also gave them financial security for future medical care and lost career potential.
For instance, we recently handled a case where a client got bad neck and back injuries after a Grubhub driver, who was messing with the app, blew a red light on Camelback Road near Central Avenue. At first, the driver’s personal insurance only offered a tiny amount, insisting the Grubhub app was off. We dug in and sent a legal demand for the driver’s dispatch logs from Grubhub, which proved he was on an active delivery. That shifted the entire case to Grubhub’s much larger commercial policy. That evidence, along with detailed reports from the client’s doctors, led to a settlement that covered all his physical therapy, the potential cost of a future surgery, and a full six months of lost wages.
What this really buys you is peace of mind. It gives you the space to focus on getting better, instead of worrying about medical bills piling up and your finances collapsing. Without this kind of strategic fight, too many people just take the first lowball offer they get because they’re desperate or don’t know any better, and they walk away with far less than they need.
Getting through a Grubhub accident claim takes hard work, legal skill, and a deep knowledge of how these specific insurance policies work. By acting fast, documenting all your losses, and hiring an experienced lawyer, you give yourself the best shot at getting a fair and complete settlement that truly covers your recovery.
What is the statute of limitations for filing a personal injury claim in Arizona after a Grubhub accident?
In Arizona, you have two years from the date of the accident to file a lawsuit for a personal injury claim, and that includes crashes with Grubhub drivers. If you miss that two-year deadline, you will almost certainly lose your right to sue for compensation forever.
Does Grubhub’s insurance cover all accidents involving its drivers?
No. Grubhub’s commercial insurance is only supposed to apply when the driver is on an active delivery, either on their way to pick up food or on their way to drop it off. If the driver is just logged in and waiting for an order, or if their app is off, their own personal car insurance is supposed to be the primary coverage. Figuring out the driver’s exact status at the moment of impact is a major part of the case.
What if the Grubhub driver was uninsured or underinsured?
This is where your own policy comes into play. If the Grubhub driver who hit you has no insurance or not enough to cover your damages, your own uninsured/underinsured motorist (UM/UIM) coverage can step in to pay. It’s an incredibly important part of your own insurance policy, especially with the confusion around delivery driver coverage.
How long does it take to settle a Grubhub accident claim in Phoenix?
It depends. A straightforward case with minor injuries might settle in a few months. But if you have serious injuries, or if we have to fight with multiple insurance companies over who is responsible, it can easily take 12 to 24 months to resolve. If a lawsuit is necessary, it can take even longer.
Can I still receive compensation if I was partially at fault for the accident?
Yes. Arizona uses a legal rule called “pure comparative fault.” This means you can still get paid even if you were partly to blame for the crash, but your final compensation will be reduced by your percentage of fault. For instance, if a jury decides you were 20% at fault, your total settlement award would be cut by 20%.