Maria, an Instacart shopper in Houston, found herself in a dire situation after a sudden accident on the I-610 Loop near the NRG Park exit. A distracted driver swerved into her lane, causing a chain-reaction collision that left her vehicle totaled and Maria with a fractured wrist and severe whiplash. Her primary concern immediately shifted from delivering groceries to understanding how she would cover medical bills and lost income. This is where the complexities of policy stacking options for Instacart Houston shoppers become critically important, offering a potential lifeline when standard coverage falls short. How can gig economy workers like Maria navigate these intricate insurance claims to secure the compensation they deserve?
Key Takeaways
- Georgia law permits policy stacking for both uninsured/underinsured motorist (UM/UIM) coverage and medical payments (MedPay) coverage, potentially increasing available compensation after an accident.
- Instacart’s occupational accident insurance provides limited coverage for injuries sustained while actively shopping or delivering, typically excluding vehicle damage and pain and suffering.
- Understanding the hierarchy of insurance claims for gig workers usually involves personal auto policy, followed by the at-fault driver’s insurance, then Instacart’s coverage, and finally any stacked UM/UIM or MedPay.
- Filing a claim effectively requires careful documentation of the accident, injuries, medical treatments, and lost wages, strengthening the case for maximum recovery.
- Consulting with a personal injury attorney specializing in auto accidents and gig economy claims is essential to identify all available policies and navigate complex negotiations.
The Accident on the Loop and Initial Confusion
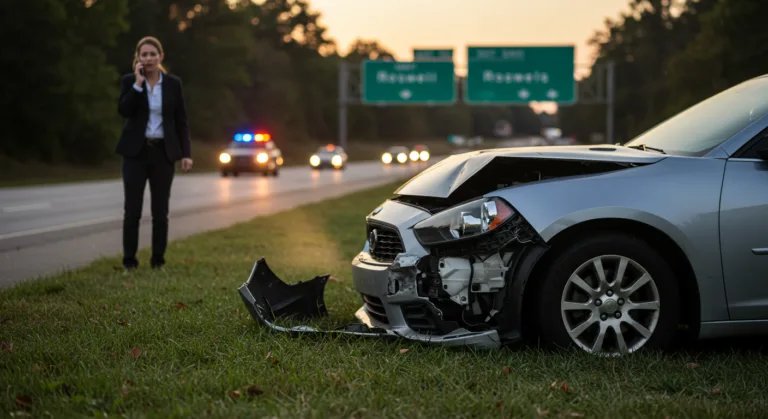
Maria had just picked up an order from a grocery store in Meyerland Plaza and was heading north on the I-610 when the accident occurred. The impact was severe, pinning her against the steering wheel. Emergency services arrived quickly, and she was transported to Memorial Hermann Hospital Southwest. While recovering, the reality of her situation began to sink in. Her car, essential for her Instacart work, was gone. Her arm would require surgery, meaning weeks, if not months, off work. The at-fault driver’s insurance, she soon learned, had minimum liability limits, barely enough to cover her initial hospital visit, let alone ongoing treatment, physical therapy, or her lost earnings.
This scenario is unfortunately common for gig economy workers. Many operate under the assumption that their personal auto insurance will cover everything, or that the platform they work for, like Instacart, has complete coverage. The truth is often far more nuanced and, frankly, less protective. Personal auto policies often have exclusions for commercial use, and platform coverages can be quite limited. For Maria, the question became: how do you bridge that gap between what’s covered and what’s needed? This is precisely where the concept of policy stacking comes into play, a legal mechanism in Georgia that can significantly increase the available insurance funds after an accident.
““This is not a pivot or a reinvention,” Melvin said. “Tyka is a continuation of the exceptional work we have always done together for over 20 years, now within a firm built entirely around representing insurers.””
Understanding Policy Stacking in Georgia for Instacart Shoppers
Policy stacking allows individuals to combine the limits of multiple insurance policies or multiple coverages within a single policy to increase the total amount available for a claim. In Georgia, this primarily applies to two types of coverage: uninsured/underinsured motorist (UM/UIM) coverage and medical payments (MedPay) coverage. Many drivers, particularly those working in the gig economy, carry multiple policies or have options for stacking that they don’t even realize exist.
Consider Maria’s situation. She had her personal auto policy, which included UM/UIM coverage. Her husband also had a separate auto policy for his vehicle, also with UM/UIM. Under Georgia law, specifically O.C.G.A. Section 33-7-11, if these policies cover vehicles owned by the same named insured or resident relatives, those UM/UIM coverages can often be stacked. This means instead of just one $50,000 UM/UIM limit, Maria might have access to $100,000 or more. This potential increase makes a substantial difference when faced with mounting medical bills and lost wages.
MedPay coverage also offers stacking possibilities. If Maria had MedPay on her policy and her husband had it on his, those limits could potentially be combined to cover medical expenses, regardless of who was at fault. This is a critical distinction from liability coverage, which only pays out if you’re at fault. MedPay is “no-fault” coverage, designed to quickly cover initial medical costs.
The Nuances of Commercial Use Exclusions
One of the first hurdles Maria faced was her personal insurer’s initial reluctance. They cited a “commercial use exclusion” in her policy, arguing that because she was driving for Instacart at the time of the accident, her personal policy did not apply. This is a common tactic by insurance companies and one that requires careful legal navigation. Many personal auto policies are indeed written with such exclusions. However, the interpretation and enforcement of these clauses can vary, and sometimes, a strong argument can be made that the exclusion does not apply, or that the insurer should still provide coverage under certain circumstances.
For instance, some policies differentiate between occasional use for a gig and full-time commercial driving. Also, if the at-fault driver is uninsured or underinsured, your UM/UIM coverage might still be triggered, even if other aspects of the personal policy are disputed due to commercial use. It’s a complex area, and one where the specific language of your insurance contract and Georgia case law become paramount.
Instacart’s Insurance Coverage: A Closer Look
While personal policies present challenges, Instacart does offer some level of insurance for its shoppers. Instacart’s primary coverage for shoppers is typically an Occupational Accident Policy. This policy is designed to cover medical expenses and lost income if a shopper is injured while actively engaged in an Instacart order. It’s not auto liability insurance and does not cover damage to your vehicle or liability for damage you cause to others’ property. It also typically has specific limits and conditions, often with a deductible.
For Maria, Instacart’s policy would likely cover some of her medical bills and a portion of her lost wages, but it wouldn’t address her totaled vehicle or the significant pain and suffering she endured. This is why understanding the interaction between all available policies is so important. The Instacart policy often acts as a secondary layer of protection, kicking in after personal health insurance or if personal auto policies deny coverage for injury-related expenses.
The Hierarchy of Claims for Gig Workers
When an Instacart shopper is involved in an accident, the order in which insurance policies respond can be confusing. Generally, the hierarchy tends to be:
- The at-fault driver’s liability insurance (if they have it and are identified).
- Your personal auto insurance, specifically your MedPay or personal injury protection (PIP) and potentially your UM/UIM coverage if the at-fault driver is uninsured or underinsured.
- Instacart’s Occupational Accident Policy, which provides specific benefits for injuries and lost income during an active order.
- Any additional stacked UM/UIM or MedPay policies available through other household members or additional vehicles.
Working through this hierarchy requires a detailed understanding of each policy’s terms and conditions, as well as Georgia insurance law. It’s not simply a matter of calling one company and expecting them to handle everything. Each insurer will likely try to minimize their payout, making it an adversarial process.
Maria’s Path to Recovery: The Importance of Legal Counsel
Feeling overwhelmed by the paperwork, the medical appointments, and the conflicting information from insurance adjusters, Maria wisely decided to seek legal counsel. She contacted a personal injury firm in Atlanta that specializes in auto accidents and workers’ compensation claims, recognizing that her situation touched on both areas. Her attorney immediately began gathering all relevant documents: police reports, medical records, wage statements from Instacart, and copies of all her and her husband’s insurance policies.
The first step for her attorney was to formally notify all potential insurers of the claim. This included the at-fault driver’s insurance, Maria’s personal auto insurer, her husband’s auto insurer, and Instacart’s occupational accident carrier. Her attorney then carefully reviewed each policy for commercial use exclusions and the specific language regarding UM/UIM and MedPay stacking.
One of the key arguments her attorney made against Maria’s personal insurer’s commercial use exclusion was that while she was driving for Instacart, the accident itself was caused by a third-party driver’s negligence, not by any inherent risk related to her delivery work that would typically be excluded. This distinction can sometimes sway an insurer, or at least open the door for negotiation.
Plus, her attorney focused on maximizing the policy stacking. By demonstrating that Maria and her husband were resident relatives and that their policies met the criteria under O.C.G.A. Section 33-7-11, they were able to argue for stacking both the UM/UIM and MedPay coverages. This significantly increased the total pool of funds available to cover Maria’s extensive medical treatment, lost income, and pain and suffering. The total available coverage jumped from what initially seemed like a paltry sum to a figure that more accurately reflected the true cost of her injuries and losses.
Negotiation and Resolution
With a clear understanding of all available coverages, Maria’s attorney entered into negotiations with the various insurance companies. This process involved presenting detailed medical bills, a prognosis from her doctors regarding future treatment, and a complete calculation of her lost wages, both past and future. The ability to stack policies provided use, as it meant more funds were available to settle the claim without protracted litigation.
After several months of negotiations, Maria reached a settlement that covered her medical expenses, compensated her for her lost income during her recovery period, and provided a fair amount for her pain and suffering. While no amount of money can truly undo the trauma of an accident, the complete settlement allowed her to focus on her physical recovery without the added stress of financial ruin. Her vehicle was replaced, and she eventually returned to work, albeit with some adjustments to her schedule.
Lessons Learned for Instacart Shoppers in Houston and Beyond
Maria’s experience highlights several critical lessons for anyone working in the gig economy, particularly those driving for platforms like Instacart:
- Review Your Personal Auto Policy Carefully: Understand any commercial use exclusions and what they mean for your coverage. Consider adding a rideshare endorsement if your insurer offers one, as this can bridge the gap between personal and commercial use.
- Understand UM/UIM and MedPay: These coverages are often overlooked but are incredibly important, especially when the at-fault driver has insufficient insurance. Maximize these limits if possible, and understand Georgia’s rules on stacking.
- Document Everything: After an accident, carefully document the scene, gather witness information, take photos, and keep detailed records of all medical appointments, treatments, and expenses. Track every hour of lost work.
- Don’t Rely Solely on Platform Coverage: Instacart’s Occupational Accident Policy is a safety net, but it has limitations. It’s not a substitute for complete personal auto insurance and strong UM/UIM coverage.
- Seek Legal Counsel Promptly: The complexities of insurance claims, especially with multiple policies and commercial use ambiguities, demand expert legal guidance. An attorney can identify all potential sources of recovery and fight for your rights. Many personal injury firms operate on a contingency fee basis, meaning you don’t pay unless they win your case.
The gig economy offers flexibility and opportunity, but it also places a greater burden on individuals to understand their insurance protections. For Instacart shoppers in Houston, or anywhere in Georgia, proactively understanding policy stacking and seeking professional advice can be the difference between financial devastation and a secure recovery after an unexpected accident.
What is policy stacking in Georgia?
Policy stacking in Georgia allows individuals to combine the limits of multiple insurance policies or multiple coverages within a single policy, primarily for uninsured/underinsured motorist (UM/UIM) and medical payments (MedPay) coverages, to increase the total amount of available compensation after an accident.
Does Instacart provide auto insurance for its shoppers?
Instacart typically provides an Occupational Accident Policy for its shoppers, which covers medical expenses and lost income for injuries sustained while actively working on an order. This policy is not auto liability insurance and does not cover vehicle damage or liability to third parties.
Can I stack UM/UIM coverage from different policies in Georgia?
Yes, under Georgia law (O.C.G.A. Section 33-7-11), if multiple auto insurance policies cover vehicles owned by the same named insured or resident relatives, the uninsured/underinsured motorist coverages from those policies can often be stacked, significantly increasing the available coverage.
What if my personal auto insurance denies coverage due to commercial use?
If your personal auto insurer denies coverage due to a commercial use exclusion, it’s critical to consult with an attorney. The applicability of such exclusions can be complex, and legal counsel can help determine if the exclusion is valid or if there are arguments to compel coverage, especially for UM/UIM or MedPay.
Why is it important for Instacart shoppers to understand policy stacking?
Understanding policy stacking is important for Instacart shoppers because it can provide significantly more financial protection than standard coverages, helping to cover extensive medical bills, lost wages, and other damages when an at-fault driver has insufficient insurance or when platform coverage is limited.