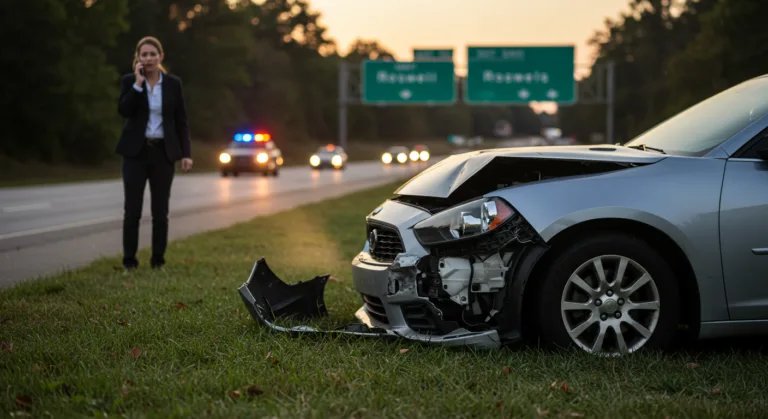
The screech of tires on Abercorn Street was the only warning. For Maria, an Uber driver grinding through a busy Saturday in Savannah, the jarring impact at the White Bluff Road intersection changed everything. Her sedan, her office and livelihood, was instantly a crumpled mess because a distracted driver blew a red light. The sting from the airbag was bad, but it was nothing compared to the fight that came next. She quickly discovered that proving her case as an Uber driver in a Savannah accident meant getting tangled in the legal mess of “independent contractor” status, a classification that can make or break your recovery.
Key Takeaways
- In Georgia, Uber drivers are almost always considered independent contractors, which means workers’ comp is usually off the table.
- The official definition of employee vs. independent contractor for workers’ comp is laid out in Georgia law, specifically O.C.G.A. Section 34-9-1.
- An Uber driver in a crash has to deal with a confusing mess of insurance policies: their personal one, Uber’s commercial coverage, and the at-fault driver’s.
- You absolutely have to document everything, injuries, every dollar of lost income, and all expenses, if you expect to get a fair settlement.
- A Georgia personal injury lawyer who knows car accidents is your best bet for sorting out the insurance and contractor status mess.
The Aftermath on Abercorn: Initial Chaos and Lingering Questions
Flashing lights cut through the Savannah dusk as emergency services swarmed the scene. Paramedics from Memorial Health University Medical Center checked on a dazed Maria while her 2022 Honda Civic sat, clearly totaled. The other driver, a shaken young man, admitted fault right there to the Savannah Police Department officer. While the immediate chaos was about police reports and making sure everyone was physically okay, Maria’s mind was already racing ahead to the practical problems. How was she going to make a living with no car? And who was going to pay the medical bills from the ER visit that had just diagnosed her with a concussion and whiplash?
Her first call to Uber’s support line offered zero comfort. After walking her through the accident report process, the conversation took a sharp turn. “You’re an independent contractor,” the rep on the phone said flatly. That one phrase would become the center of her entire struggle. The flexibility of being a gig worker is great, until you realize it strips you of the protections regular employees get when they’re hurt on the job.
Independent Contractor vs. Employee: A Critical Distinction in Georgia
Everything for Maria came down to her job title. In Georgia, the line between an employee and an independent contractor isn’t just words on a page. It has huge financial and legal consequences, especially for workers’ comp and who’s held liable. For Uber drivers, the courts have consistently sided with the view that they are independent contractors. What this means in practice is that Uber doesn’t have to provide workers’ compensation coverage, a safety net that most employees count on if they get hurt at work.
Georgia law, specifically O.C.G.A. Section 34-9-1, lays out the criteria for who counts as an employee, and it often boils down to how much control the company has over the time, manner, and method of your work. Uber obviously has some control through its app and rating system, but courts have generally decided it’s not the same level of control a boss has over a W2 employee. It’s a legal gray area that leaves gig workers like Maria in a terrible spot after a crash.
“People think just because you’re doing work for a big company, you’re automatically an employee with all the protections,” explains a legal expert on Georgia labor laws. “But for ride-share drivers, that flexibility they love comes at a huge price, they lose those standard protections. That’s exactly where the fight starts: finding someone to pay for everything when workers’ comp isn’t an option.”
Were you in a car accident?
Insurance adjusters are trained to settle fast and pay less. Most car accident victims leave an average of $32,000 on the table.
Working through the Insurance Labyrinth: Personal, Uber, and Third-Party Policies
Suddenly Maria was tangled in a web of insurance. She had her own personal policy, but like most, it had an exclusion for commercial driving. Then there was Uber’s insurance, which is broken down into confusing “periods” based on what you’re doing in the app:
- Period 0: You’re offline. Your personal insurance is the only thing that applies.
- Period 1: You’re logged in, waiting for a ride. Uber gives you some liability coverage ($50,000 per person, $100,000 per accident for bodily injury, and $25,000 for property damage) but only if your personal policy says no.
- Period 2: You’ve accepted a ride and you’re driving to the pickup. Now Uber’s big $1 million third-party liability policy is active.
- Period 3: You’ve got a passenger in the car. The $1 million liability policy is still on, plus you get uninsured/underinsured motorist coverage and contingent complete and collision coverage (but you have to pay a deductible).
Maria’s crash happened in Period 2. She had just accepted a ride for someone near Forsyth Park and was on her way. That meant Uber’s $1 million policy was technically active, but that policy is designed mostly to protect other people (like passengers or pedestrians). For Maria’s own car, the policy only provides “contingent” coverage, a weak promise that it might pay out if her personal insurance denies the claim, and even then she’d still be on the hook for a large deductible.
Her biggest worries were her medical bills, the income she was losing every day, and how to replace her car. The main target had to be the at-fault driver’s insurance. In this case, it was GEICO. But getting money out of an insurance company is never easy. They’re pros at minimizing payouts, questioning the severity of injuries (like a concussion), and arguing about how much income you’ve actually lost.
The Fight for Fair Compensation: Documenting Everything
Maria knew this was too complicated to handle herself. After getting her initial medical care, her first smart move was to start a paper trail. She created a detailed file with all her medical appointments, every physical therapy session at the Candler Hospital Rehabilitation Center, and receipts for every related expense. She also pulled her past Uber earnings statements to create a clear record of her average weekly income before the wreck put her out of work.
If you’re in this spot, you have to be this detailed. There’s no other way. Insurance adjusters are paid to pick claims apart, and if you don’t have hard proof of your medical costs and financial losses, they have every reason to offer you pennies or deny you outright. Maria also had photos from the scene, pictures of her wrecked car, and photos of her own injuries. She even got contact info for a couple of people who saw it happen, just in case.
For a complicated Georgia car wreck claim, especially with the whole Uber independent contractor problem, you need a lawyer who gets it. Firms like Bader Law, a Georgia personal-injury and workers’ compensation firm, deal with these cases all the time. Their attorneys know how to sort out the confusing mess between your personal policy, Uber’s different coverage periods, and the at-fault driver’s insurance to make sure no money is left on the table. For drivers like Maria, having a legal team that can explain your rights and the insurance details is essential. You can learn more about their approach to Car Accidents in Georgia.
Legal Strategy: Pursuing the At-Fault Driver and Challenging Assumptions
Maria’s lawyer had a clear plan: go after the at-fault driver’s insurance first and foremost. Because Georgia is an “at-fault” state, the person who causes the wreck is legally responsible for the damages. Her attorney assembled a powerful demand package with the police report, all the medical records, her lost wage calculations, and even an expert opinion on her long-term recovery from the concussion. The package laid out all her damages in black and white: medical bills, lost earning potential, pain and suffering, and the value of her totaled car.
At the same time, they dug into the fine print of Uber’s insurance policy. While that policy is good for protecting passengers, getting it to pay for a driver’s own injuries and lost income is tough, especially when the at-fault driver has their own coverage. The one time it becomes truly useful for the driver is when the at-fault person is uninsured or underinsured. In that scenario, Uber’s uninsured/underinsured motorist coverage can be a financial lifesaver.
That “independent contractor” label is a huge problem for workers’ comp, but it’s not always impossible to challenge. If a lawyer can find evidence that Uber controlled a driver’s work so much that it looked more like a traditional job, they could argue for reclassification. Realistically, though, these are uphill legal battles that require a lot of time, money, and very specific facts that most cases don’t have.
For Maria, the smartest move was to go hard after the clearly at-fault driver. Her attorney entered into tough negotiations with GEICO, immediately rejecting their first lowball offers. They hammered the adjuster with the facts: the severity of her concussion, her ongoing need for physical therapy, and the real financial pain of being unable to earn a living. They also made it clear they were preparing to file a lawsuit in Chatham County Superior Court if a fair settlement wasn’t offered. Just showing you’re ready and willing to go to court is often what it takes to get an insurance company to make a serious offer.
Resolution and Lessons Learned
It took months of back-and-forth, but with a mountain of medical evidence and clear liability, Maria’s lawyer secured a settlement from the at-fault driver’s insurance. The final amount covered all her medical bills, paid her for the income she lost while recovering, and gave her the money she needed to replace her totaled vehicle. It was a long and frustrating process, but her obsessive documentation and her legal team’s refusal to back down made all the difference.
Maria’s story is a warning for any Uber drivers face who get into an accident. The freedom of gig work comes with the heavy responsibility of understanding your own legal status and insurance coverage. That “independent contractor” label is everything, and it shapes the entire fight for compensation. If you’re a ride-share driver in Georgia, you need to understand what this means *before* a crash happens, and you need to know when it’s time to call in a pro.
Getting paid fairly after a wreck like this, especially when you’re caught between ride-share insurance rules and your contractor status, takes serious preparation and a skilled lawyer. Don’t ever underestimate what thorough paperwork and persistent advocacy can do. They’re the best tools you have. For more information on dealing with Georgia injury claims, it’s always smart to get legal advice. If you’re an Atlanta accident victim, you have to protect your rights.
So what’s the real difference between being an ’employee’ and an ‘independent contractor’ if you drive for Uber in Georgia?
It’s all about protections. Employees are typically covered by workers’ compensation if they get hurt on the job and may get other benefits. As an independent contractor in Georgia, an Uber driver almost never gets workers’ compensation from Uber after a crash.
What insurance actually covers me if I’m hit while my app is on but I’m waiting for a ping?
That’s “Period 1.” If your personal insurance won’t cover it (and it probably won’t), Uber’s limited liability coverage may kick in. This is typically $50,000 per person/$100,000 per accident for bodily injury and $25,000 for property damage. It won’t cover your own car’s damage in this phase, though.
Can I actually get paid for the time I can’t work after a crash?
Yes, you can make a claim for lost wages, but you have to prove what you were making with your Uber earnings statements or tax records. This claim is made against the at-fault driver’s insurance policy, not directly from Uber as a workers’ comp benefit.
What’s the most important paperwork to collect after a wreck as an Uber driver?
The police report is number one. After that, you need all your medical records for every treatment, photos of everything (the scene, your car, your injuries), your Uber earnings statements to prove lost income, and every email or letter you exchange with the insurance companies. A running list of every single accident-related expense is also a must-have.
Do I really need a lawyer after an Uber accident?
With all the moving parts, the different insurance policies, your independent contractor status, and the inevitable arguments over who pays for what, it’s a really good idea. A personal injury lawyer who knows these specific types of cases can cut through the confusion and fight the insurance companies for you, which is the best way to get fair compensation for your injuries and all your losses.