Key Takeaways
- When an Amazon Flex driver in Dallas gets in a wreck, they hit a legal grey area over liability because they aren’t quite employees or independent contractors.
- Laws like Georgia’s O.C.G.A. Section 34-9-1 show why gig workers get blocked from workers’ comp, they’re classified as independent contractors which makes injury claims a nightmare.
- After a crash, an Amazon Flex driver in Dallas must immediately gather evidence, photos, witness info, and medical records, because that’s the only way to build a legal claim.
- Amazon’s insurance for Flex drivers isn’t standard commercial auto coverage. It’s full of limitations and specific requirements drivers have to know before an accident happens.
- To deal with the insurance mess and sue the people responsible in Dallas, a driver needs a personal injury lawyer who knows the ins and outs of gig economy accident cases.
Working as an Amazon Flex driver in Dallas provides flexible income, but it also throws you into a legal minefield the second you get into an accident. The gig economy is booming, but it leaves people in a very vulnerable spot when it comes to liability and getting paid for injuries after a crash. So are Flex drivers really protected when they’re out delivering packages on Dallas’s crowded roads?
The Ambiguous Status of Gig Economy Drivers in Dallas
The biggest problem for an Amazon Flex driver in Dallas after a wreck is their employment status. Are they employees or independent contractors? That single distinction changes everything about their legal options. Employees usually get workers’ compensation benefits, but independent contractors are on their own. Amazon, like most gig companies, calls its Flex drivers independent contractors, and that classification has massive legal consequences for your insurance coverage, who is held liable, and your right to sue for damages.
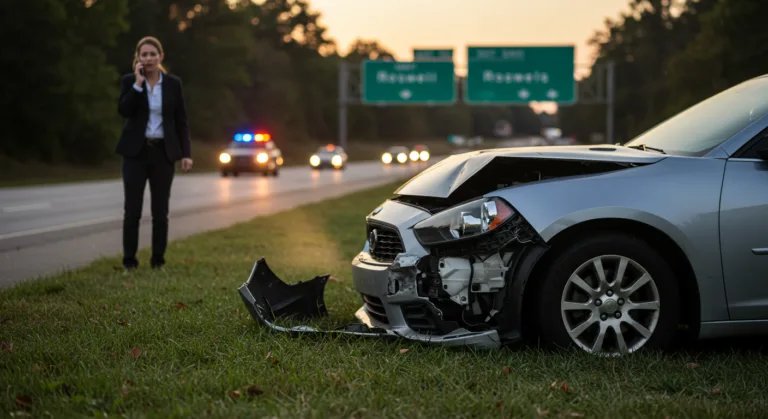
Picture a driver on Stemmons Freeway (I-35E) near downtown Dallas, in the middle of a delivery route, when another car plows into them. If they were a regular employee for a delivery company, the next steps would be straightforward: they’d file a workers’ comp claim and also pursue a claim against the driver who hit them. For an Amazon Flex driver, it’s a mess. Amazon’s insurance is usually contingent, which means it only starts paying after your own personal auto insurance denies the claim, and even then, it typically only applies when you are actively on a “delivery block.” This “on-block” vs “off-block” status is a huge deal. If you get hurt between deliveries or while you’re just logged into the app waiting for a route, Amazon’s insurance might not cover you at all. This forces drivers into a position of having to document every minute of their work and read the fine print of Amazon’s policy, which almost no one does until it’s too late.
Working through the Insurance Maze After an Amazon Flex Accident
When an Amazon Flex driver gets into a wreck in Dallas, the aftermath is a confusing mess of different insurance policies. The first one is the driver’s own personal auto insurance. The problem is, most personal policies have an exclusion for commercial activity, and delivering packages for Amazon definitely qualifies. This means your own insurer will probably deny your claim once they find out you were working, which is a devastating surprise for many drivers.
Then you have Amazon’s commercial auto insurance, which is provided by a third-party company. This “Flex Auto Policy” is supposed to provide liability coverage for injuries and damage to other people, along with uninsured/underinsured motorist coverage and collision coverage, but there are major strings attached. The policy might only cover you from the second you pick up a package to the second you drop it off. Any personal stop you make in between, even for a minute, could void your coverage entirely. You have to understand the exact terms. For example, if you’re seriously injured in a crash on Mockingbird Lane and end up at Baylor University Medical Center with huge bills, Amazon’s policy limits might not be enough to cover everything, especially since your personal policy already denied the claim. That leaves a huge financial gap for drivers who thought they were covered.
| Factor | Traditional Employee | Amazon Flex Driver (Dallas) |
|---|---|---|
| Worker Classification | Employee | Independent Contractor |
| Workers’ Compensation Eligibility | Typically eligible | Generally excluded (per O.C.G.A. Section 34-9-1) |
| Personal Auto Insurance Coverage | Usually covered | Often excluded for commercial activity |
| Amazon’s Insurance Coverage | N/A | Contingent, “on-block” only |
| Liability Complexity | Relatively clear path | Highly convoluted, “grey area” |
Workers’ Compensation and the Gig Economy in Georgia
Although this case is in Dallas, the legal fight over workers’ comp for gig workers in states like Georgia is a good example of what’s happening everywhere. In Georgia, the Workers’ Compensation Act (specifically O.C.G.A. Section 34-9-1) defines who counts as an “employee.” Independent contractors are flat-out excluded. The Georgia State Board of Workers’ Compensation looks at how much control a company has over the way a person does their job to decide their status. This is the main battleground for gig economy companies.
For an Amazon Flex driver hurt on the job, a workers’ comp claim is almost guaranteed to be denied because of their contractor status. So if a driver suffers a spinal injury from being rear-ended on I-635 near the Dallas North Tollway, they can’t count on workers’ comp to pay their medical bills or cover lost wages. They’re forced to file personal injury lawsuits against the at-fault driver or try to get money from Amazon’s very limited commercial policy which we’ve already seen has serious restrictions. This lack of a safety net is a huge problem for gig economy workers nationwide, leaving them in financial ruin after a work injury. It’s nothing like traditional employment, where those benefits are standard. From my experience, this classification is what leaves injured drivers facing huge medical bills with no idea how they’ll pay them.
What to Do After a Dallas Accident: The Proof is on You
If you’re an Amazon Flex driver in a Dallas accident, what you do right after the crash will make or break any legal claim you might have. The burden of proof is all on you, especially when dealing with confusing gig economy insurance. First, get to safety and get medical help right away, even for what seems like a minor ache. Adrenaline masks pain, and serious injuries like concussions or whiplash can show up hours or even days later. Having a medical professional document your injuries from the very beginning is something you absolutely have to do.
Next, start gathering evidence at the scene. Take a ton of photos and videos of everything: the crash scene, the damage to every car, the road conditions, and any injuries you can see. You need to get contact information from everyone involved, names, phone numbers, insurance info, and license plates. Also, make sure you get the names and numbers of any witnesses. Their story can be critical for proving who was at fault if there’s a dispute later. Call the police and get a report filed. That official document is an unbiased account that insurance companies often demand. Finally, you must save records of your Amazon Flex activity. That means taking screenshots of the app showing you were on an active delivery, keeping your delivery manifests, and saving any messages with Amazon support. This is the only way you can prove you fall under Amazon’s policy. Your claim is already complicated, but without these records, it becomes almost impossible to win.
Legal Recourse for Injured Amazon Flex Drivers in Dallas
When an Amazon Flex driver in Dallas gets hurt in a wreck, getting legal help usually means attacking the problem from a couple of angles. Because they are independent contractors, they can’t file a workers’ comp claim against Amazon. The main path to getting money is a personal injury lawsuit against the driver who caused the accident. This means proving the other driver was negligent and demanding money for medical bills, lost income, and pain and suffering. That process can take a long time and you need a lot of evidence to make your case.
Beyond suing the other driver, you might be able to get money from Amazon’s commercial insurance policy. But, as we’ve seen, that depends on proving you were on an active delivery. Fighting these claims requires someone who really understands insurance law and the tricks of gig economy policies. Insurance companies will often dispute the claim, argue about how bad your injuries are, or just deny coverage based on some fine print. This is where you need a personal injury attorney. A lawyer can parse the dense policy language, fight with the insurance adjusters, and file a lawsuit if they won’t pay fairly. They might also see if there’s a way to hold Amazon liable, maybe by arguing their safety rules were lacking, though that’s a tougher fight. The truth is, without a lawyer, injured gig workers are left to fight giant insurance companies by themselves, and that’s a fight they almost never win.
The hurdles an Amazon Flex driver in Dallas must clear after an accident are immense, mostly because of the independent contractor status and the weak, conditional insurance that gig companies offer. You have to understand this complicated situation, immediately start gathering evidence, and get legal help to protect your rights and get what you’re owed. Don’t just assume your personal insurance, or even Amazon’s, will cover you. Prepare for a fight.
Employee vs. independent contractor for Amazon Flex drivers: what’s the difference?
An employee gets benefits like workers’ compensation and unemployment, and the company tells them how to do their job. An independent contractor which is how Amazon classifies its Flex drivers, is running their own business, sets their own schedule, and doesn’t get those benefits. This difference is huge for liability and insurance after a crash.
Will my personal car insurance cover an Amazon Flex accident in Dallas?
Probably not. Most personal auto policies have a “commercial use” exclusion, which means they won’t cover an accident if you were being paid to deliver packages for Amazon Flex. You need to read your policy carefully or talk to your insurance agent to know for sure what your limits are.
What insurance does Amazon provide for Flex drivers?
Amazon offers a contingent commercial auto policy. It’s supposed to offer liability coverage for others’ injuries and property damage, uninsured/underinsured motorist coverage, and sometimes collision coverage. But it only works when a driver is on an “active delivery block” and usually only pays after your personal insurance has denied the claim.
What evidence should I collect after a Dallas Amazon Flex accident?
After getting medical help, you need to collect photos and videos of the scene, all vehicle damage, and your injuries. Get contact info for every driver and any witnesses. Get the police report number. And most importantly, take screenshots from the Amazon Flex app to prove you were on an active delivery. Your medical records are also essential.
Can an injured Amazon Flex driver get workers’ compensation?
Almost never. Because they are classified as independent contractors, Amazon Flex drivers typically can’t get workers’ compensation benefits in most states, including in cases governed by laws like Georgia’s. Injured drivers have to sue the at-fault driver or try to get a payout from Amazon’s limited commercial policy, which has very strict rules.